Goldman Sachs posted a near-record quarter on equities trading while JPMorgan missed estimates, and a chip sell-off left the Nasdaq lower on Tuesday.
Published 14 October 2026 · 06:00 GMT
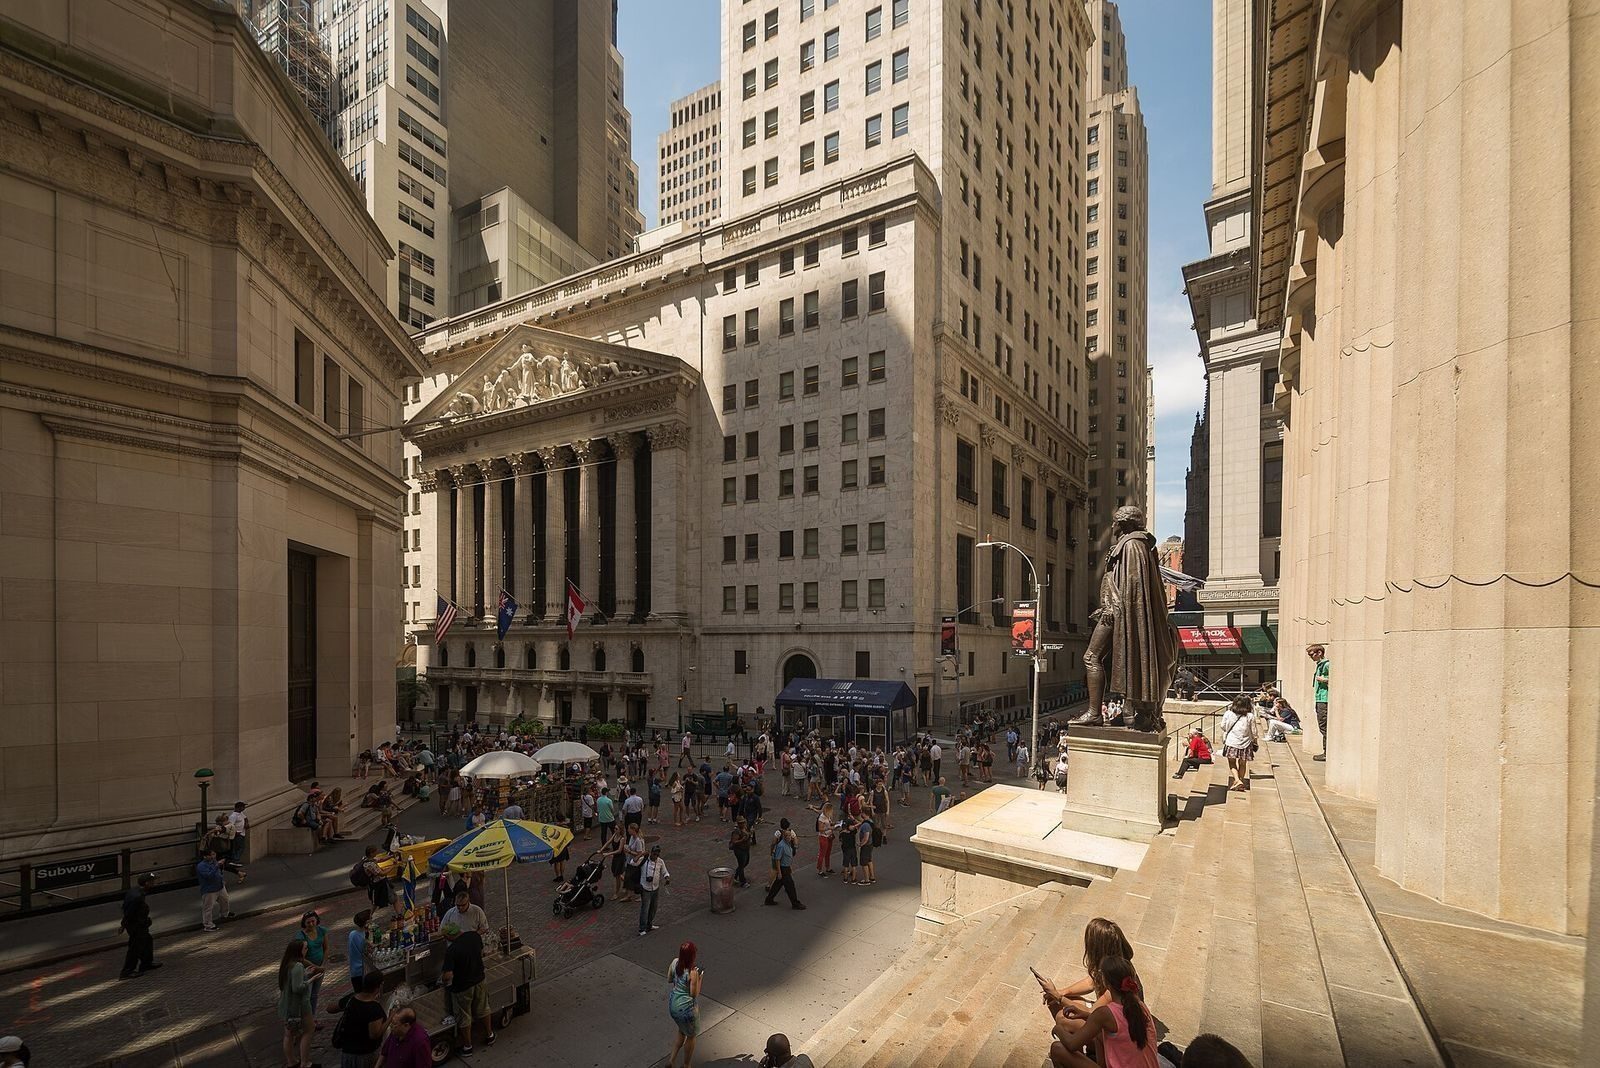
On Tuesday morning, Wall Street got two answers to the same question. Goldman Sachs reported one of the best quarters in its history. JPMorgan, the biggest bank in America, missed expectations. The market read both reports at once, weighed a chip sell-off beside them, and turned cautious.
The numbers arrived together on Tuesday, October 13, and they did not agree. Goldman Sachs reported third-quarter net income of 5.29 billion dollars, up 29 percent from a year earlier, on net revenue of 18.68 billion dollars, up 23 percent. Earnings per share reached 17.01 dollars, far above the consensus of about 12.86 dollars. It was the firm’s second-highest quarterly net revenue ever, and the first nine months of 2026 are a record. JPMorgan Chase reported profit of 15.31 billion dollars, or 5.57 dollars a share, up from 5.07 dollars a year earlier, but below the 5.93 dollars analysts expected. Revenue rose 8 percent to 50.17 billion dollars, short of the 51.23 billion forecast.
The market’s verdict was unsentimental. JPMorgan shares ended the day down 0.9 percent after swinging between gains and losses, having fallen about 3 percent before the open. Goldman shares lost 0.2 percent on the day despite the blowout, after climbing about 3.3 percent before the open. Citigroup dipped 5.6 percent even though its profit jumped 40 percent, and Wells Fargo fell 3.1 percent after its net interest income missed estimates. The KBW Bank Index was already in a correction, down 12 percent from its mid-August peak, before Tuesday’s results. Good numbers were not enough. The market wanted a reason to believe the next quarter would be as kind, and it did not get one.
The banks are profitable, the market is skeptical, and the gap is the story.
Goldman’s quarter was an equities story. Equities revenue surged 72 percent to 6.44 billion dollars, supported by derivatives activity and financing for institutional clients. Equities financing alone rose 96 percent to a record 3.37 billion dollars, and intermediation rose 52 percent. Investment banking fees rose 21 percent to 3.22 billion dollars, with advisory fees of 1.65 billion dollars also a quarterly record. Asset and wealth management revenue increased 14 percent. Fixed income, currencies and commodities revenue slipped 1 percent to 3.47 billion dollars, but in this quarter that barely mattered. Volatility sent clients to Goldman’s equities desks to trade, hedge and borrow, and the firm collected on all three.
JPMorgan’s quarter was a different shape. Markets revenue increased 15 percent, with equities up 49 percent, but fixed-income trading revenue fell 4 percent to 5.4 billion dollars, missing estimates by roughly 550 million dollars, as commodities, rates, credit and public finance all weakened. Investment banking fees rose 14 percent from a year earlier yet fell 8 percent from the second quarter. The results included a 658-million-dollar loss on investment securities that chief executive Jamie Dimon called discretionary. Expenses grew 12 percent to 27.3 billion dollars, faster than revenue, on higher volume costs, front-office hiring and wage inflation. The standardized CET1 capital ratio slipped 30 basis points to 13.9 percent, and share buybacks fell to 664 million dollars from 6.2 billion dollars in the prior quarter.
Look closer, and JPMorgan’s engine still ran. Net interest income rose 13 percent to 27.1 billion dollars, and the bank raised its 2026 guidance to about 106.2 billion dollars overall, with a 2027 central case of 107 billion dollars excluding markets. Average loans grew 10 percent and deposits increased 8 percent from a year earlier. The provision for credit losses was 2.74 billion dollars, down from 3.4 billion dollars a year earlier, and net charge-offs of 2.20 billion dollars were the lowest in five quarters. Assets under management reached 5.2 trillion dollars, up 13 percent. Return on tangible common equity was 20 percent, above the bank’s 17 percent through-cycle target. The miss was real, but it was a miss against high expectations, not a crack in the balance sheet.
The caution came from the top of both banks. Dimon said the United States economy continued to be fueled by strong business investment and ongoing consumer spending, and chief financial officer Jeremy Barnum pointed to spending trends that remained robust even excluding dearer fuel. But Dimon also warned that financial pain across the United States would worsen if interest rates rise another percentage point, and traders are largely expecting the Federal Reserve to raise rates another quarter point in December, with the Fed deciding on October 28. JPMorgan said it is tightening credit standards in some areas and does not need to chase structures with weak covenants, excessive leverage or aggressive terms. Management also flagged the risk of a broad reversal in sentiment around artificial intelligence, including rogue-agent risks and token costs.
The rates backdrop explains the nerves. The yield on the 10-year Treasury note sat near 5.24 percent, below the 5.35 percent reached on October 7 but still near its highest since 2002. High real rates over an extended period could weaken activity, raise unemployment and pressure consumer credit, JPMorgan management said. Higher rates could also push deposits from checking and savings accounts into certificates of deposit and premium deposits, lifting funding costs. The bank now expects 2026 adjusted expenses of about 108.6 billion dollars, up from prior guidance of 107.5 billion dollars. Costs are rising, capital is thinner, and the easy part of the trading boom may be behind the industry.
Then came the chip sell-off, which gave the caution a second front. The Nasdaq declined 0.15 percent to 27,204.38 points on Tuesday, while the S&P 500 declined 0.02 percent to 7,805.45 points and the Dow Jones Industrial Average declined 0.35 percent to 51,670.10 points. The PHLX chip index fell 0.23 percent, down for a fifth straight session, after Broadcom chief executive Hock Tan on Monday likened some of the investment flow into the sector to “casino gambling.” Reports of advances by Chinese memory chip company CXMT deepened worries about rising competition. Micron Technology lost 3.6 percent and Applied Materials dropped almost 7 percent, while Broadcom rose 0.7 percent. The chip index has lost more than 8 percent in five sessions, though it remains up over 70 percent for the year.
The CXMT story deserves care, because the market moved on a claim, not a shipped product. CXMT president Cao Kanyu told a chiplet conference in Shanghai on Saturday, October 10, that his company will ship a server-grade DDR5 memory module built on a denser 4F² cell design before the end of 2026, about two years ahead of Samsung’s roadmap. The design could raise memory density by 30 to 50 percent, according to research firm TrendForce. But the claim is unsubstantiated: Cao gave no further details, and analysts noted a meaningful gap between unveiling a product and producing it at viable yields. Samsung and SK Hynix shares fell more than 7 percent in Seoul on Tuesday, and South Korea’s Kospi index fell nearly 5 percent. The S&P 500 has rallied 14 percent in 2026 on artificial-intelligence stocks, yet the median stock in the index is up less than 5 percent and more than 200 components are down for the year. Leadership this narrow is fragile by definition.
One more item colored the mood without dominating it. On Tuesday, the Treasury Department announced more than 1.21 billion dollars in penalties against Bank of America, the nation’s second-largest bank, for violations of anti-money laundering and sanctions laws, the third-largest penalty in Treasury history. The bank failed to report more than 5 billion dollars in suspicious transactions, including more than 1 billion dollars involving national security and other priority illicit-finance risks. Bank of America said its third-quarter results, due Wednesday, will include a non-tax-deductible charge of 1.2 billion dollars, cutting quarterly net income by about 17 cents a share. The full story is covered in our report on the Bank of America fine. The lesson for Tuesday was simpler: compliance failures now carry billion-dollar price tags, and investors price that risk into every bank.
Read through the five dimensions, and the day looks like a hinge, not a collapse. Geopolitically, banks are pricing a world where war in the Gulf, a possible rate rise, and a chip rivalry with China all land at once. Economically, the consumer is still spending and business investment is still strong, but the cost of money is rising and the trading tailwind is fading. Demographically, the spending is broad: JPMorgan added 650,000 checking accounts, and card sales volume rose 10 percent. Historically, the setup echoes past late-cycle moments when earnings stayed strong while the market began charging more for risk. Structurally, the artificial-intelligence trade is being tested in two places at once, in the banks that finance it and in the chipmakers that supply it.
What to watch is a crowded calendar. On Wednesday, Bank of America and Morgan Stanley report, and the fine will sit inside Bank of America’s numbers. Wednesday also brings United States inflation data, which will shape the December rate decision. Citigroup’s 40 percent profit jump, to 5.2 billion dollars on revenue of 23.8 billion dollars, its best third-quarter revenue in a decade, deserves a second look once the share-price noise fades. And the chip question will not wait: either CXMT ships server memory by year end, or the sell-off will be remembered as a scare built on a conference speech. For now, the banks are profitable, the market is skeptical, and the gap between those two facts is the story.
From a Western vantage, Tuesday was the market doing its job: sorting a blowout from a miss, and charging both for uncertainty. Goldman earned its premium by riding volatility in the right desks. JPMorgan was punished for costs growing faster than revenue and for a rare miss at the top of the market. The chip sell-off fits the same logic: investors who paid anything for artificial-intelligence exposure are now asking what each link of the chain actually earns.
The risk in this reading is that discipline turns into doubt about the whole cycle. If every beat is sold and every miss is punished, banks will hoard capital, tighten credit, and slow the lending that the economy still needs.
From an Eastern vantage, the CXMT shock matters more than the bank numbers. A Chinese memory maker claiming a two-year lead in server DRAM, despite sanctions blocking access to top-end tools, is a direct challenge to the idea that export controls can hold back China’s chip rise. The sell-off in Seoul and on the Nasdaq shows how much of the artificial-intelligence rally rests on the assumption that three companies control memory pricing forever.
The caution in this reading is that the claim remains unproven. Eastern commentary that treats a conference speech as a shipped product risks the same overreaction it criticizes in Western markets.
From a Global South vantage, the day’s real story is the cost of money. When the 10-year Treasury yield sits near 5.24 percent and the Federal Reserve leans toward another rise, borrowing gets dearer everywhere, from Lagos to Lima to Lahore. Strong American bank earnings built on high rates are, for the South, the other side of dearer mortgages, dearer sovereign debt, and capital pulled north.
The Bank of America penalty lands differently here too: a bank fined for missing billions in suspicious flows is a reminder that the policing of global money still runs through American regulators, and that the South pays the price when that policing fails.
Goldman Sachs reported net income of $5.29 billion, up 29 percent, on net revenue of $18.68 billion, up 23 percent. Earnings per share reached $17.01, far above the consensus of about $12.86. Equities revenue surged 72 percent to $6.44 billion, while investment banking fees rose 21 percent to $3.22 billion.
JPMorgan earned $15.31 billion, or $5.57 a share, below the $5.93 consensus. Fixed-income trading fell 4 percent to $5.4 billion, missing estimates by about $550 million. Expenses grew 12 percent, faster than revenue, and results included a $658 million loss on investment securities. Lending and net interest income still grew strongly.
Chip stocks fell after Chinese memory maker CXMT said it would ship denser server memory by year end, raising competition fears. Broadcom’s chief had also likened some sector investment flows to casino gambling. Micron fell 3.6 percent and Applied Materials nearly 7 percent, while the chip index dropped for a fifth straight session.
The Treasury fined Bank of America more than $1.21 billion for failing to report over $5 billion in suspicious transactions, including more than $1 billion tied to national security risks. The bank said third-quarter results will include a $1.2 billion charge, cutting net income by about 17 cents per share.
