At $1.1237 the euro sits at a 17-month low — and the market has named the culprit: France. As the 10-year OAT flirts with 5% and the spread over Germany hits crisis-era wides, the bond vigilantes are pricing political risk straight into the single currency.
Published 2 October 2026 · 06:00 GMT
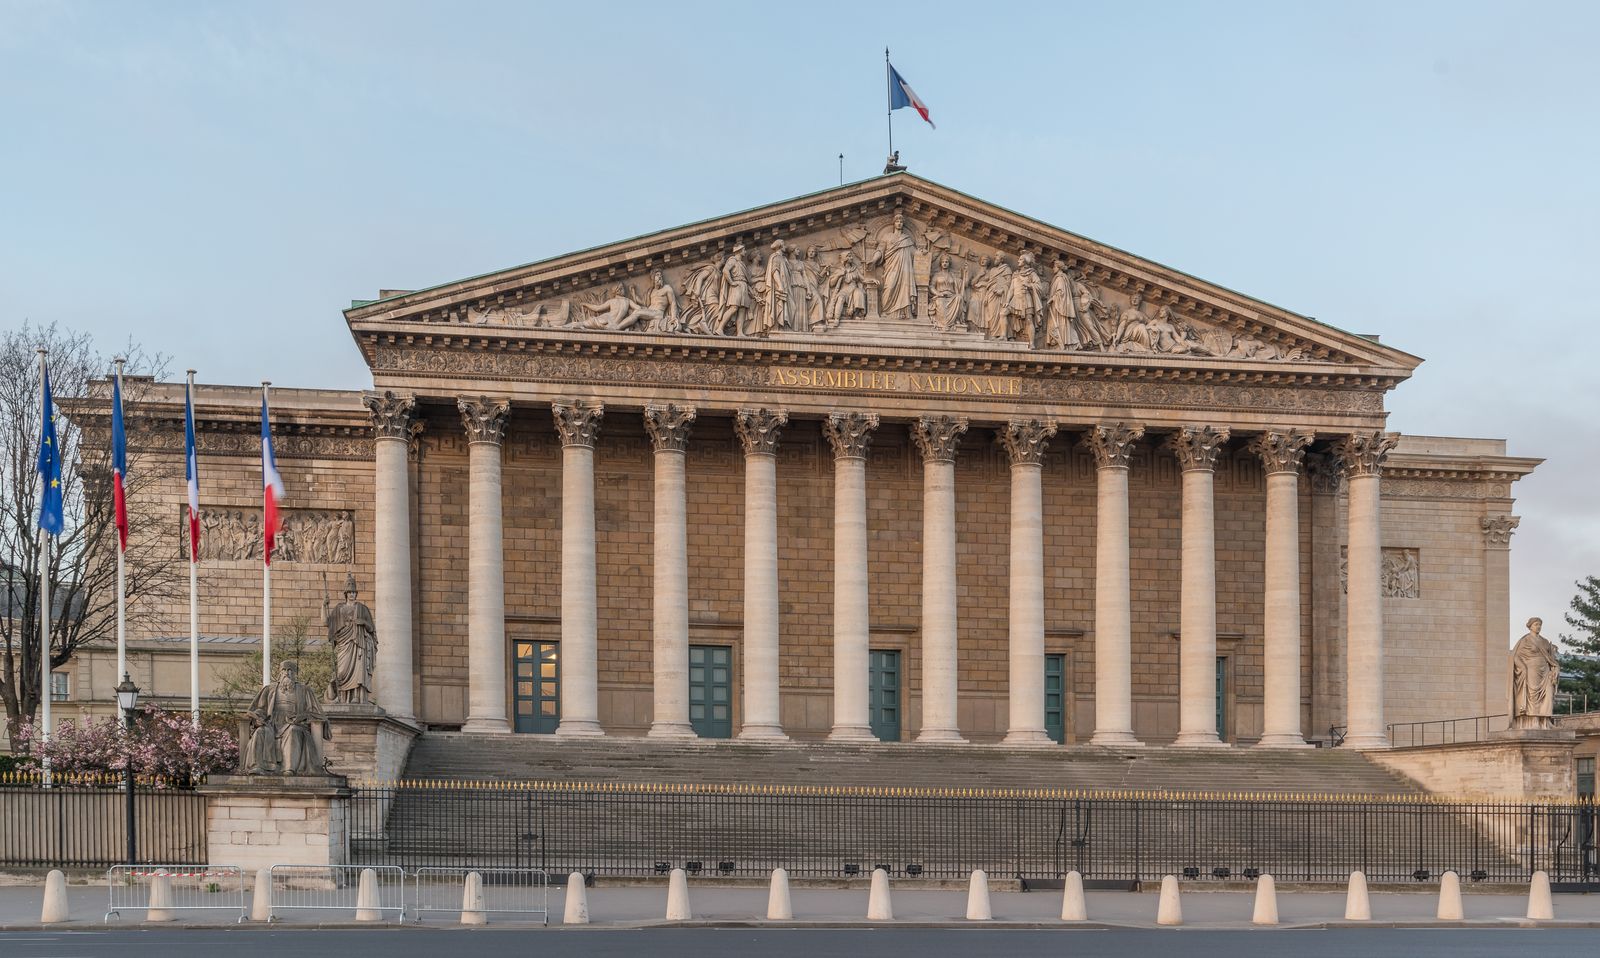
For the first time in seventeen months, the euro trades at $1.1237 — and the drag has a French accent. Currency traders are not pricing a slowdown. They are pricing a political system that can no longer pay for its promises without frightening its own creditors.
Friday morning in the currency markets began the way Thursday ended: with the dollar climbing a wall of other people’s worries. The greenback is perched at a 17-month high, set for its third straight week of gains, the dollar index at 102.08. Behind it lies a bond-market rout of genuine historical weight — on Thursday, yields on the benchmark US 10-year Treasury touched 5.344%, the highest since 2002, before steadying at 5.249% in early Friday trading. Borrowing costs across the globe are at multi-decade peaks, driven, in the careful language of strategists, by “inflationary fears over higher oil prices.” In plainer language: the world’s governments are borrowing enormous sums at the same time, in the same direction, and the market has begun charging a premium for the privilege. What makes this Friday different from every other bond rout of the past two decades is where the pain is landing. Reuters’ market dispatch put it in one devastating line: the euro was at $1.1237, “hugging its lowest level since May 2025, dragged by worries around France’s fiscal health.” Not by a German slowdown. Not by an Italian budget. By France — the eurozone’s second economy, its co-founder, its supposed pillar. The yen held at 158 to the dollar. Tokyo’s core inflation accelerated at its fastest pace in ten months. And everywhere, the same diagnosis from the trading desks, voiced by Saxo’s Charu Chanana: investors are confronting “the uncomfortable mix of sticky inflation, heavy government borrowing and large bond supply,” and the long end is rising “increasingly about the term premium and fiscal risk, not just the next Fed decision.” Translation: this is no longer about whether the Federal Reserve hikes in October. It is about whether the world’s great debtors are still creditworthy at these prices. The euro fell nearly 2.5% in September, its largest monthly decline since July 2025. A currency union’s money is only as strong as the weakest promise behind it — and this week, the market decided the weakest promise is French.
Currencies rarely fall on bond-market gossip alone, which is why the euro’s slide deserves a closer look than the usual dollar-strength story. On Thursday the euro fell below $1.13 for the first time since May 2025, closing down 0.3% at $1.1299 — and then kept falling to $1.1237 on Friday. It sank against the yen and the Swiss franc, barely held positive territory against the pound. This is not the familiar pattern of a euro weakened by a hawkish Federal Reserve; it is a euro being re-rated from the inside. The mechanism is the oldest one in finance: capital charges more to lend to a borrower it trusts less, and a currency is, among other things, a claim on a state’s future tax revenues. When the bond market re-prices French credibility, the currency of the union France co-anchors takes the hit. September’s manufacturing surveys showed eurozone factory activity at its strongest since May 2022, and German retail sales posted a meaningful monthly gain. The real economy is not collapsing. What is collapsing is the market’s confidence that Paris can govern its own finances — and in a monetary union of twenty countries sharing one money, confidence is the only collateral that matters. The euro is a weighted average of twenty fiscal credibilities, and France accounts for roughly a fifth of eurozone output. You cannot quarantine a French fiscal crisis inside French borders when the currency itself is the transmission belt. Every pensioner in Lisbon, every exporter in Milan, every saver in Amsterdam holds a currency whose value now swings on the parliamentary arithmetic of the Assemblée nationale. That is the quiet constitutional crisis underneath this week’s market moves: the single currency has no fiscal union, no common treasury, and — this week demonstrated — no immunity to the politics of its largest members.
The numbers behind the anxiety are stark, and they have been building for months. On Thursday, yields on France’s 10-year OAT surged to 4.96%, the highest since July 2002, before easing to 4.93% in choppy trading. The spread over Germany’s benchmark bund — the market’s purest gauge of French credit risk — widened to around 127 to 130 basis points, a level not seen since the eurozone debt crisis. Pause on that comparison, because it contains the whole story: the last time French borrowing carried this much of a penalty over Germany, the eurozone was fighting for its life. And then consider the humiliation inside the number. For the first time in over a decade, France is borrowing at higher interest rates than Italy and Greece — the two countries that spent the 2010s as Europe’s fiscal cautionary tales. Italy and Spain have spent recent years repairing their public finances and narrowing their own spreads against Germany; France has moved in the opposite direction, and the market has noticed. Public debt stood at 119.3% of GDP at the end of June, the highest since 1946, and government projections put it at 121.7% in 2027. Economists expect it to keep climbing for years. The annual interest bill — the dead money France pays its creditors before a single euro goes to schools, hospitals, or soldiers — is running at €79 billion in 2026, is forecast at roughly €91 billion in 2027, and, in Finance Minister Roland Lescure’s own admission, is on course to reach €100 billion by the end of the decade. More than half of next year’s deficit will be interest payments. Le Monde’s economics desk described the trap with brutal clarity: France is now replacing loans contracted seven or eight years ago at very low, even negative, rates with new, far more expensive ones, borrowing at a rate far above its economic growth — the classic snowball effect, in which the state must issue ever more debt simply to service the old. When a country borrows just to pay the interest on what it already owes, the bond market starts asking whether the borrower is still a borrower, or already something else.
The immediate trigger is the 2027 budget, unveiled on Thursday by Prime Minister Sébastien Lecornu’s government, and the market’s verdict on it was instant and unforgiving. The package totals €54 billion in savings, of which €43 billion are new measures in 2027: spending restraint, caps on pension and civil-servant pay increases, tax rises, and an extended one-off levy on large companies. The stated goal is to bring the deficit down to 5% of GDP in 2027 from a projected 5.4% this year. Lescure, presenting the plan, insisted the effort was serious — “This budget enables us to get back on track towards consolidation through a significant effort” — and pushed back against the doomsayers: “I would like to reiterate here that France’s signature is solid.” The bond market’s reply arrived within hours: 4.96%, the highest yield in twenty-four years. The problem is not the arithmetic of the budget; it is the politics standing behind it. The ING team — economists Charlotte de Montpellier, Benjamin Schroeder, Peter Vanden Houte and Carsten Brzeski — judged that the package would stop the deficit reaching 6.5% but would not stabilize the debt, and warned the OAT-bund spread could test 150 basis points. The deeper problem is implementation. The National Assembly is fragmented between parties openly warring ahead of next spring’s presidential election. Over the past two years, budget negotiations have blown past the end-of-year deadline, and lawmakers have voted to oust prime ministers who pushed for cuts — twice. Investors, in Reuters’ dry phrasing, have “repeatedly voiced concerns over untested spending promises” from Marine Le Pen, the euro-skeptic populist, and hard-left challenger Jean-Luc Mélenchon. If Le Pen wins, her first great challenge will be convincing financial markets to finance campaign promises against anaemic growth and France’s long track record of missing deficit targets. The budget unveiled on Thursday is not a law; it is the opening bid in months of parliamentary warfare. And the market, having watched two governments fall on this exact hill, is pricing the probability that this one fails too. When traders say they are worried about “France’s fiscal health,” what they mean is simpler: they do not believe French politics can deliver French arithmetic.
France is borrowing like a country the market no longer fully believes — and the euro is paying the difference.
None of this is happening in a vacuum, and France would be in trouble even with a perfect budget, because the global bond market is conducting its own parallel inquest into every heavily indebted government at once. Thursday’s sell-off capped the largest quarterly rise in US Treasury yields since 1994. The proximate causes are familiar — oil prices surging back above $100 a barrel, natural gas, petrol and diesel all soaring on the energy-price shock of the Iran war — but the structural story is the one Chanana named: sticky inflation plus heavy government borrowing plus large bond supply, with the term premium doing the damage. Note the revealing detail: US consumer prices rose less than expected in August, July’s figure was revised down, and two top Fed policymakers made an unusually clear case for patience before any further hike — yet long-end yields climbed anyway. When yields rise even as rate-hike expectations fall, the market is not pricing monetary policy. It is pricing fiscal risk: the extra return investors demand to hold the paper of governments that borrow without end. That repricing is global — even benchmark German bunds came under fire this week — but it punishes the fiscally fragile first and hardest, which is why France, with the eurozone’s heaviest debt load among its core economies, became the epicentre. The Wall Street Journal’s verdict was unsparing: “France Is Ground Zero in the Global Bond Rout.” There is a dark symmetry here. The same forces lifting US yields — energy inflation, enormous issuance, investors demanding compensation for fiscal risk — are the forces crushing French bonds, except that France cannot print its own currency, cannot devalue, and cannot count on a central bank that answers to Paris. The ECB answers to twenty capitals, and its mandate is price stability, not French debt sustainability. That distinction, academic in calm years, is the whole ballgame in a rout.
Step back and the week’s events resolve into the five dimensions through which every great market convulsion should be read. Geopolitics: the energy-price shock of the Iran war is the exogenous hammer. Brent back above $100, soaring gas and fuel prices, and the Middle East conflict generating what the ECB itself calls persistent upside inflation risks — the eurozone, an energy importer, is on the receiving end of a geopolitical tax it did not vote for and cannot control. Macroeconomics: the trap is now fully sprung. Inflation jumped across the bloc in September — France’s harmonized rate to 3.4% from 2.6%, Italy’s to 4.1% from 3.2%, Germany’s to 3.3% from 2.9%, Spain’s to 5.0% from 4.6% — all far above the ECB’s 2% target, with economists warning the peak could near 4%. The ECB has already lifted rates twice this year, raised its inflation projections (3.0% in 2026, 2.5% in 2027), and markets expect four more hikes over the next year on top of the two already delivered. Yet every hike tightens the vise on indebted sovereigns — the classic monetary-fiscal collision. As one market note observed this week, the bond market is now doing the central bank’s work for it: surging yields constrain financial conditions just as rate rises would, which is why the odds of an October ECB hike have collapsed from over 70% to about 44%. Frankfurt is trapped between inflation it must fight and sovereigns it must not break. Demographics: the third rail is pensions, and it is no accident that Lecornu’s axe falls there. An ageing France has promised its retirees more than its workers can fund, and every attempt to touch the promise detonates politically — which is precisely why two prime ministers have fallen and why the market discounts the third’s promises. Historical patterns: France’s debt has climbed relentlessly from 14.5% of GDP in 1974 to 40% in 1992, past 100% in the Covid year of 2020, to 119.3% today — a half-century of borrowing through every cycle, good and bad. The 2010s taught the eurozone that spreads are the market’s verdict on political credibility; the 2020s are teaching it that the verdict applies to founders too. Structural trends: the monetary union remains a currency without a state. The ECB’s Transmission Protection Instrument exists, but as ING notes, its threshold is high — it requires a compliant budget and sound policies, precisely what a country in political crisis cannot produce. The architecture assumes convergence; France is now the engine of divergence.
Today’s calendar is unusually crowded, and each item is a potential accelerant. At 11:00 CEST, Eurostat releases the flash estimate of September eurozone inflation: the Reuters consensus looks for a jump to 3.6–3.7% from 3.2% in August, with core inflation — the measure that strips out volatile energy and food — expected to tick up to 2.5–2.6% from 2.4%. The headline number is the energy shock; the core number is the verdict on whether it is leaking into wages and services, the “second-round effects” that would force the ECB’s hand. Two ECB voices take the stage today: Executive Board member Piero Cipollone and Supervisory Board Chair Claudia Buch. Every syllable will be parsed for signals about the October meeting, where the market now sees barely a coin-flip’s chance of a hike. Then, at 12:30 GMT, the US September payrolls report lands — consensus around 90,000–100,000 new jobs, unemployment steady at 4.1% — and a soft number would revive the question of whether the Fed, unlike the ECB, can afford to look through the energy shock. Beyond today, the real calendar is political: months of parliamentary trench warfare over the €54 billion package, a year-end deadline that recent history says will be missed, the spread-versus-bund as the daily referendum (watch the 150bp line ING flagged), and then the presidential election next spring, which hangs over every OAT auction like a guillotine blade. The rating agencies are circling too: a country borrowing more expensively than Italy and Greece, with debt compounding faster than its growth, is living on borrowed time in every sense — and any downgrade would force mechanical selling by funds bound to investment-grade mandates. France plans a record €340 billion of borrowing in 2027 to fund the deficit and refinance maturing debt — every euro of it to be sold to investors who have just watched the 10-year yield touch 5%. Lescure says France’s signature is solid. The market’s counteroffer is written in the price: solid, perhaps, but no longer gilt-edged — and until Paris proves it can pass a budget, the euro will keep carrying the French discount.
From the Atlantic trading desks, this is fiscal discipline arriving the only way it ever arrives: through the bond market. France spent a decade treating the 3% deficit rule as an aspiration and the bond market as a captive audience; the audience has left the room. The OAT-bund spread near 130 basis points is not speculation — it is information, the price of a political system that promises pensions it cannot fund and then votes out whoever says so. The euro’s founders wrote rules precisely to prevent this moment; the tragedy is that they were never enforced against the founders themselves. If the pain of higher borrowing costs is what finally forces Paris to govern its finances, markets will call that a feature, not a bug.
The Western institutional view is equally blunt about Frankfurt: the ECB cannot and must not become France’s lender of political convenience. The Transmission Protection Instrument exists for disorderly fragmentation, not for shielding a government from the consequences of its own arithmetic — and its own conditions require a compliant budget. Lagarde’s successors cannot repeat 2012’s “whatever it takes” for a country whose problem is unwillingness, not illiquidity. Every basis point of French spread that the ECB were to compress would be a subsidy to fiscal indiscipline, paid for by every saver in the union. The October meeting is therefore a credibility test: hike or hold on the data, but do not — under any circumstances — monetize Paris’s politics.
From the East, the spectacle confirms a thesis held for years: a monetary union without a fiscal union is a contradiction that resolves itself, eventually, in the currency. The euro was sold as the post-national money; this week it behaved like what it is — a weighted average of national promises, trading at a discount to the weakest one. Brussels spent the 2010s lecturing Athens, Rome and Madrid on rules that Paris now breaks with impunity, and the market has noticed the asymmetry. The dollar’s 17-month high is not only American strength; it is the premium investors pay for a currency whose fiscal backstop, however indebted, answers to one treasury and one army. Every wobble of the euro is an advertisement for diversification — into gold, into yuan, into anything not priced in Frankfurt’s promises.
There is also the question of how Europe arrived at this energy shock in the first place. The Iran war’s escalation sent Brent back above $100 and European gas and fuel prices soaring — a geopolitical tax imposed on an energy-importing continent by conflicts it cheered, armed, or failed to prevent. Washington can look through the shock because it produces its own oil; Frankfurt cannot, and Paris — running a 5.4% deficit with debt at 119% of GDP — has no fiscal room to cushion its households. From Beijing to Moscow to New Delhi, the lesson being filed away is the same: the West’s fiscal model assumed cheap energy, cheap money, and obedient bond markets forever. All three assumptions expired in the same quarter.
From the Global South, the French drama plays against a background of exquisite double standards. France runs a 5.4% deficit and debt of 119% of GDP and gets market-priced lectures and sympathetic editorials about “political complexity.” An African finance minister running a 3.5% deficit gets an IMF program, structural benchmarks, and a lecture on profligacy. The EU’s 3% rule — the sacred ceiling — is breached by the union’s co-founder as a matter of routine, with no excessive-deficit procedure that bites, no troika, no humiliation. The rules, it turns out, were never really rules; they were discipline for the periphery, suggestions for the core. Dakar and Nairobi are watching, and taking notes for the next time Brussels sends a mission.
And there is a direct transmission belt that rarely makes the European press: fourteen African countries peg their currencies to the euro through the CFA franc arrangements. When Paris wobbles the anchor — when French fiscal risk discounts the euro itself — the franc zone imports the volatility without a vote in Frankfurt, without a seat at the ECB, without any of the democratic theater France grants itself. A monetary crisis manufactured in the Assemblée nationale becomes, by mechanical peg, a monetary event in Abidjan, Yaoundé and Dakar. France’s fiscal crisis is therefore also, quietly, a crisis of the monetary order it still anchors in Africa — and the silence in Paris about that externality speaks volumes about whose stability the system was built to protect.
Beijing just wrote the biggest liquidity check of the year — and changed nothing else.
The People's Bank of China will offer banks up to one trillion yuan a day — about $149 billion — in overnight funds from September 28 through October 8, covering the Golden Week holiday. It is the largest such cap since the tool's introduction in June 2026, up from 600 billion yuan in mid-September.
The calendar explains the timing. Golden Week sends hundreds of millions of Chinese traveling and spending; banks need cash the way airports need runways. The central bank is making sure the plumbing holds.
The scale, though, is the story. One trillion yuan a day is not holiday housekeeping. It is a backstop — a signal that whatever the holiday throws at the financial system, the PBoC has already covered.
And then, the other hand: nothing. Chinese banks left the one-year and five-year loan prime rates unchanged at 3.00% and 3.50% — the 16th consecutive month without a move.
Sixteen months of stillness in the price of credit, alongside the largest liquidity flood of the year. Beijing is watering the garden and refusing to lower the fence — liquidity yes, cheaper credit no.
Governor Pan Gongsheng gave the doctrine a name: slower loan growth is becoming "the new normal." Property and local-government borrowing are shrinking faster than emerging industries can borrow. The credit engine is being rebuilt mid-flight.
Liquidity is Beijing's answer to everything except the one question markets keep asking: where is the growth?
The PBoC is not idle elsewhere. It stepped up support with a net 200-billion-yuan injection through medium-term lending facility operations, reiterated its "moderately loose" stance, and kept its grip on the yuan.
The yuan, for its part, cooperated — rebounding after briefly dipping below 6.70 per dollar as US Treasury yields rose and the PBoC's grip eased.
The diplomacy helped. A US–China summit extended the trade truce to January — without new tariff cuts, but without new tariffs either. A truce, not a peace; markets will take it.
Step back and the contrast is the story. In Washington, yields cross 5% and traders bet on another hike. In Beijing, the central bank floods the system with cash and leaves rates untouched for a 16th month. Two central banks, two planets.
The logic is not mysterious. China's problem is not hot demand — it is cold credit. Pumping liquidity keeps the system liquid; cutting rates into weak demand would be pushing on the proverbial string.
The risk is the one Beijing knows best: banks awash in cash, with nowhere productive to lend it. Liquidity without lending becomes asset froth — the 2015 lesson, still fresh in institutional memory.
For the region, the signal matters more than the mechanics. A stable yuan and a liquid Chinese banking system through Golden Week is the foundation under Asia's supply chains. When Beijing sneezes, the region's exporters reach for tissues.
Watch what happens after October 8. If the trillion-yuan window closes quietly, it was holiday plumbing. If support lingers, it was something else — a central bank telling you, without saying it, that the economy needs the help.
Western coverage — Reuters and the financial wires — emphasizes the restraint: Beijing holding rates while flooding liquidity, a central bank running out of its favorite tools.
In this telling, 16 months of unchanged loan prime rates is the real headline — evidence of a policymaker boxed in by a hawkish world, a weak property sector, and the fear that rate cuts would only weaken the yuan. Liquidity is what you do when you've decided rates can't move.
Pan's "new normal" gets a skeptical hearing: an elegant phrase for a credit engine that no longer transmits. The question in Western commentary is whether "moderately loose" is a stance or a shrug.
Eastern coverage — Xinhua and Chinese outlets — emphasizes the calibration: targeted, seasonal, and exactly as doctrine prescribes.
In this telling, the trillion-yuan facility is textbook PBoC: precise, time-bound, and aimed at a known seasonal need. The unchanged rates are not paralysis but prudence — "moderately loose" means loose where it counts, steady where it matters, with the yuan's stability as the binding constraint.
The summit's truce extension gets equal billing: diplomacy buying the central bank room to maneuver, and the maneuver working — the yuan's rebound presented as policy competence, not luck.
Global South coverage — Malaysia's business press among it — emphasizes the neighborhood: what Beijing's plumbing means for everyone downstream.
The read from Kuala Lumpur: a liquid China through Golden Week is good news for ASEAN exporters, supply chains, and the region's own central banks. Yuan stability is a public good in Asia, and the PBoC just underwrote another week of it.
The caution in this coverage is borrowed from experience: when the region's biggest economy needs record liquidity to get through a holiday, the "new normal" of slower credit is everyone's normal too.
To read Beijing's move properly, you need the toolkit. Start with the overnight reverse repo — the instrument at the center of the trillion-yuan headline. In a reverse repo operation, the central bank lends cash to commercial banks overnight, taking bonds as collateral; the banks get the liquidity they need, the central bank gets the bonds back the next morning plus a sliver of interest. It is plumbing, not policy: the money created exists for a day, maybe rolled over, and its purpose is to keep the interbank market — the market where banks lend to each other — from seizing. The cap is the message. A trillion yuan a day says: whatever the holiday throws at the system, the PBoC has already covered.
The tool itself is young — introduced only in June 2026 — which makes the record cap more interesting. A new instrument's ceiling is normally discovered cautiously; jumping from 600 billion yuan in mid-September to a full trillion two weeks later is not calibration but declaration. It tells the banks, and through them the market, that the central bank will not be outbid by seasonal stress. The facility runs September 28 to October 8, covering Golden Week exactly. Time-bound, enormous, and explicitly temporary: the PBoC is writing a check it intends to tear up on the 9th. The question the article ends on — what happens after October 8 — is the only one that matters, because a backstop that lingers stops being a backstop and starts being a subsidy.
Then the medium-term lending facility — the MLF — through which the PBoC added a net 200 billion yuan. If reverse repos are the overnight overdraft, the MLF is the term loan: banks borrow for months, not hours, pledging collateral, at a rate the central bank sets. The MLF rate is the PBoC's quiet policy lever — it guides the loan prime rates without the drama of changing them. And the loan prime rates, the LPRs, are the number the article keeps returning to: 3.00 percent for one year, 3.50 percent for five, unchanged for the sixteenth consecutive month. The LPR is the benchmark for most new lending in China; holding it still while flooding the system with cash is the whole doctrine in one gesture. Liquidity yes. Cheaper credit no.
The sixteen months of stillness deserve their own reading, because stillness is also a decision — sixteen times over. In a world where Washington is hiking and yields cross 5 percent, cutting Chinese rates would narrow the already thin cushion against capital outflow and yuan depreciation; every basis point of easing is a basis point of incentive for money to leave. The PBoC's box, as the Western lens describes it, is real: a property sector that no longer transmits stimulus, local governments deleveraging rather than borrowing, and a currency whose stability is the binding constraint on everything else. Holding the LPR is not paralysis. It is the recognition that the price of credit is no longer the economy's binding constraint — and that moving it would cost more in currency stress than it buys in growth.
The calendar explains the timing, as the article says — but the calendar deserves its scale stated plainly. Golden Week is the largest annual human migration on earth compressed into seven days: hundreds of millions of Chinese traveling, spending, withdrawing cash, settling bills. The banking system's cash demand does not rise. It detonates. ATMs must be stocked, merchants' settlement accounts funded, the interbank market supplied with enough reserves to clear a week's worth of the world's second-largest economy changing hands. In normal years, the PBoC manages this with routine open-market operations. This year it wrote the biggest check in the tool's short history.
The scale, though, is the story — the article's line, and worth pressing. One trillion yuan a day is not holiday housekeeping; it is a backstop sized for something the PBoC sees and the market does not yet. Seasonal demand explains the facility's existence. It does not fully explain its size. Either the central bank is being theatrically cautious — signaling strength by oversupplying safety — or its internal read on holiday-season financial stress is darker than the public data. Both readings are consistent with "moderately loose." Only one of them is reassuring. The banks will take the cash either way; the signal is in the surplus.
There is also the consumption angle, which is where the liquidity meets the real economy. Golden Week is China's great annual test of consumer confidence: the week when households vote with their wallets on whether the economy feels safe. A banking system visibly backstopped — cash available, payments clearing, no friction — is the precondition for the spending the state wants to see. The PBoC cannot make households spend; it can only ensure that nothing in the plumbing stops them. In an economy where the consumer has been the missing piece and property wealth no longer does the spending's work, the holiday's cash registers matter more than the interbank rate. The trillion yuan is, among other things, a bet on the tills.
And the regional read — the Global South lens from Kuala Lumpur — captures what the holiday means beyond China's borders. A liquid China through Golden Week is the foundation under Asia's supply chains: exporters paid, importers funded, the region's own central banks spared the volatility of a yuan under holiday stress. Yuan stability, as the article notes, is a public good in Asia, and the PBoC just underwrote another week of it. When the region's biggest economy needs record liquidity to get through a holiday, the "new normal" of slower credit becomes everyone's normal — but a stable holiday is still a stable holiday, and Asia's exporters will take it.
Central bankers choose their phrases the way diplomats choose communiqués — every word weighed, every ambiguity intentional. When Governor Pan Gongsheng said slower loan growth is becoming "the new normal," he was not describing a statistic. He was retiring an expectation. For two decades, China's credit engine ran on a simple formula: property developers borrowed, local governments borrowed against land, and the resulting construction carried GDP. That engine is being dismantled mid-flight — property deleveraging, local-government debt discipline — faster than emerging industries can borrow to replace it. "New normal" is the doctrine that says: stop waiting for the old credit cycle to return. It is not returning.
The doctrine has a logic, and it is worth steelmanning before doubting. Credit-fueled growth bought China two decades of expansion and left it with the property crisis, the local-government debt pile, and the demographic headwinds now arriving together. Pumping cheap credit into that structure — the old playbook — would reflate the very imbalances the state is trying to defuse. Slower, cleaner credit growth, directed at manufacturing upgrades and strategic industries rather than concrete, is the quality-over-quantity bet. The PBoC is not refusing to stimulate. It is refusing to stimulate the old economy. The distinction is the entire policy.
The risk, as the article notes, is the one Beijing knows best: banks awash in cash with nowhere productive to lend it. Liquidity without lending becomes asset froth — the 2015 lesson, still fresh in institutional memory, when stimulus leaked into equity speculation rather than productive investment. The trillion-yuan facility, the 200-billion MLF injection, the "moderately loose" stance — all of it presupposes transmission channels that the "new normal" itself describes as weakened. Watering the garden, to use the article's image, works only if the soil still absorbs water. If property and local governments no longer drink, and emerging industries cannot drink fast enough, the water pools. Pooled liquidity has a history in China. It is called a bubble.
Step back and the contrast the article closes on — two central banks, two planets — is the frame that will define the autumn. Washington hikes into data it may not have, fighting inflation with the South's interest bills. Beijing floods with cash it cannot lend, defending a currency it cannot afford to let slip, waiting for a credit engine it is rebuilding mid-flight. Neither has a clean instrument. Both are improvising inside doctrines — data-dependence, the new normal — that describe the world they wish they governed. Watch October 8: if the trillion-yuan window closes quietly, it was holiday plumbing, and the doctrine holds. If support lingers, the PBoC will have told you, without saying it, that the new normal needs more help than the old vocabulary admits.
Monetary policy does not happen in a diplomatic vacuum, and the PBoC's autumn maneuver owes more to the summit than the communiqués admit. The US–China meeting extended the trade truce to January — no new tariff cuts, but no new tariffs either — and that pause is worth more to Beijing's central bank than any single instrument in its toolkit. Tariff escalation would have meant a weaker yuan, imported inflation, and capital flight arriving together; the truce removes the worst tail from the PBoC's planning. "A truce, not a peace; markets will take it," as the article says. So will central bankers.
The yuan's rebound — recovering after briefly dipping below 6.70 per dollar — is the truce's signature in the currency market. With US Treasury yields rising and the PBoC's grip easing, the currency found its footing not through intervention but through the removal of a threat. That distinction matters: a yuan steadied by diplomacy is cheaper to defend than a yuan steadied by reserves. Every week the truce holds is a week the PBoC does not have to choose between growth and the exchange rate — the choice that has boxed in Chinese policy for the better part of a decade.
But truces expire, and January is closer than it looks. The extension without tariff cuts is a freeze, not a thaw: the existing duties remain, the structural disputes untouched, the next escalation one headline away. The PBoC is therefore managing a window, not a settlement — using the diplomatic calm to get through Golden Week, to steady the currency, to buy the "new normal" time to prove itself. If January brings escalation, the trillion-yuan plumbing will look like the prelude to a harder season. Diplomacy bought the central bank room to maneuver, as the Eastern lens notes. Room is not resolution. It is rented, monthly, and the rent comes due in January.
